facebook twitter instagram linkedin google youtube vimeo tumblr yelp rss email podcast phone blog search brokercheck brokercheck Play Pause

Keen On Retirement™

Insights Blog & Podcast

Focused insight on timely, relevant topics. Start planning your retirement. 


Subscribe now & never miss a blog or podcast

Thank you for submitting your information. Please make sure we are on your safe sender list so you don’t miss our emails.


SUBSCRIBE

Smart Strategies to Maximize Your Charitable Giving Thumbnail

Smart Strategies to Maximize Your Charitable Giving

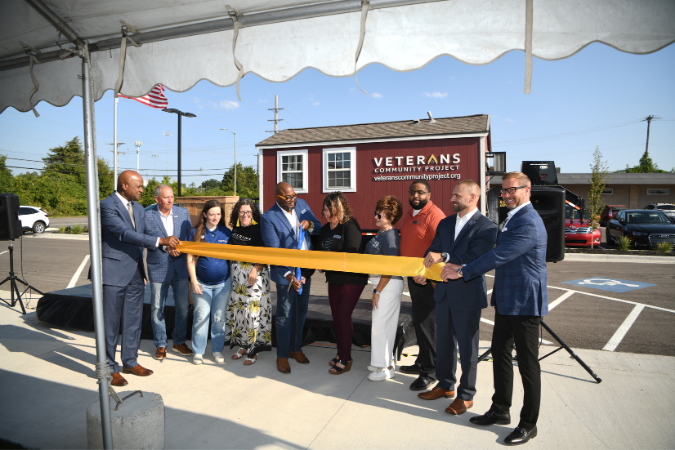
Giving back is one of our core values at Keen Wealth. Every year, my wife Carissa, who leads our Keen Community Impact Committee and the Keen Wealth Foundation, works with the committee to bring philanthropic opportunities to our broader team. Together, we identify key initiatives to support through fundraising, volunteer work, and our financial expertise. If you visit our offices during the week and see a couple of empty desks, it's a good bet that our team members are pitching in at one of these causes and trying to make our community a little brighter. I'm especially grateful for our relationship with the Veterans Community Project (VCP), which is working to end homelessness among veterans by building "tiny homes" and offering outreach to our heroes. Keen Wealth has contributed over $500,000 to the VCP's mission, provided hundreds of hours of community service, and helped found and continues to volunteer at its "Operation Clay Storm" skeet and trap shooting fundraiser. I was honored to be a part of the ribbon-cutting ceremony when the VCP broke ground on their new Veterans Navigation Campus, which will expand the support services they're able to offer veterans in our community. On today's episode, we follow up on a recent webinar I co-hosted with VCP Co-Founder & Chief Project Officer Brandonn Mixon and Keen Wealth Senior Financial Planner Jeb Flynn and discuss giving strategies that can help folks do the most good for the causes that matter most.
Read More
What Should You Hold Onto—and What Should You Let Go Of—in Retirement? Thumbnail

What Should You Hold Onto—and What Should You Let Go Of—in Retirement?

In financial planning, we sometimes refer to your working years as the "accumulation years." A large part of your time is spent working and earning so that you can support your family, achieve milestones like buying a house, and secure your financial future. But during those years, you're "accumulating" more than money. You're gaining relationships, hobbies, interests, skills, experiences, memories, and, yes, possessions. By the time you reach retirement, your life is probably as full as it's ever been. Too full, maybe. As you move through the various stages of retirement, your identity is going to change along with your interests and priorities. And part of change is letting go so that you can make room for new people and new experiences that are going to make every step of your journey more fulfilling.

Read More
Don’t Let Outdated Money “Rules” Turn Your Retirement Plan into an Antique Thumbnail

Don’t Let Outdated Money “Rules” Turn Your Retirement Plan into an Antique

"Save more than you spend" sounds like a timeless piece of money advice, as true today as it was two hundred years ago. But in the mid-1800s, many folks believed you needed to spend your money as soon as possible. In fact, saving too much back then could lead to financial ruin! That's just one example of how Americans' attitudes about money have evolved throughout history. But it's not just rules of thumb and hand-me-down wisdom that's changed. It's the nature of money and our relationship to it. On today's show, we welcome author Joseph S. Moore to discuss his new book, How to Get Rich in American History: 300 Years of Financial Advice That Worked (& Didn't), and the surprising ways five money philosophies have shifted over time.

Read More
Six Questions to Ask Before Changing Your Retirement Plan Thumbnail

Six Questions to Ask Before Changing Your Retirement Plan

In my previous post, I explained why a 30-year retirement plan cannot be treated as a "one and done" checklist. From unexpected health events to shifting personal priorities, your life should determine how and when your financial plan needs to adjust, not the other way around. But not every change requires a new financial strategy. And that's where the true tension in retirement planning lies. On the one hand, underestimating the effects of a meaningful change could put your long-term security at risk. On the other hand, overreacting to every market dip, unsettling headline, or argument with your spouse about money can cause lasting damage to your wealth. The goal for retirees should be thoughtful adaptation, not constant reaction. Before you overhaul your portfolio, ask yourself these six questions to determine if your plan truly needs an adjustment.

Read More
The Adaptable Retirement Part 2: Retirement Planning Isn’t “One and Done” Thumbnail

The Adaptable Retirement Part 2: Retirement Planning Isn’t “One and Done”

Your life and career haven't progressed in a straight line. Retirement won't either. But that's a misconception, or maybe a hope, that so many folks build into their retirement plans: that, after decades of ups and downs, happy surprises and serious challenges, retirement is going to coast along on autopilot. Hopefully, you have decades of retirement ahead of you. And those years are going to be just as unpredictable as any other period of your life, with one major new variable guaranteed. You won't have a paycheck from employment to rely on. Without the reassurance that more money is coming at the end of the month, too many seniors start making emotional money moves in the moment, whether they're facing a market dip or an unplanned home repair. That's not the kind of adaptability I was describing in part one of this blog series. I'm suggesting that if you view retirement planning as an ongoing process, you should be able to reroute when necessary. And, just as importantly, you'll have a decision-making framework that will help you distinguish between genuine warning sirens and noise you can ignore.

Read More
What Does Great Retirement Planning Actually Look Like? Thumbnail

What Does Great Retirement Planning Actually Look Like?

A comprehensive retirement plan usually includes a lot of important documents. Charts and graphs. Monte Carlo simulations. Annual rate of return projections. Lifetime tax liability. Legacy plans. But a comprehensive retirement plan isn't just documents. It's a dynamic framework for making the best possible decisions for you, your family, your money, and your life for decades to come. And as important as the numbers printed in black and white are to that framework, I believe that the true strength of a retirement plan is measured by its durability and by the confidence it gives seniors to live their best lives during their Golden Years.

Read More