
Smart Strategies to Maximize Your Charitable Giving
Giving back is one of our core values at Keen Wealth. Every year, my wife Carissa, who leads our Keen Community Impact Committee and the Keen Wealth Foundation, works with the committee to bring philanthropic opportunities to our broader team. Together, we identify key initiatives to support through fundraising, volunteer work, and our financial expertise. If you visit our offices during the week and see a couple of empty desks, it's a good bet that our team members are pitching in at one of these causes and trying to make our community a little brighter.
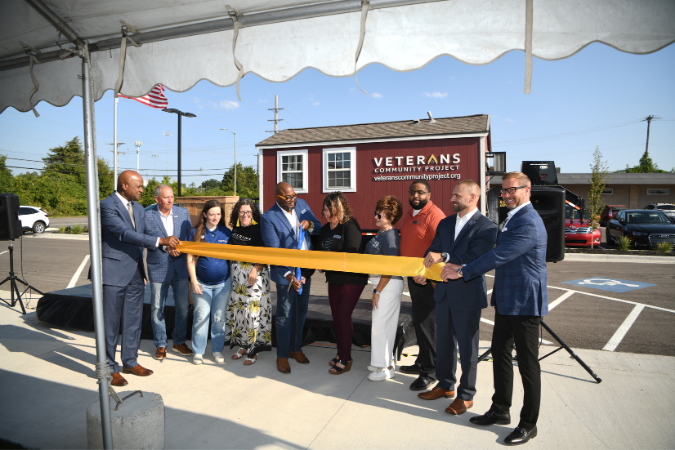
I'm especially grateful for our relationship with the Veterans Community Project (VCP), which is working to end homelessness among veterans by building "tiny homes" and offering outreach to our heroes. Keen Wealth has contributed over $500,000 to the VCP's mission, provided hundreds of hours of community service, and helped found and continues to volunteer at its "Operation Clay Storm" skeet and trap shooting fundraiser. I was honored to be a part of the ribbon-cutting ceremony when the VCP broke ground on their new Veterans Navigation Campus, which will expand the support services they're able to offer veterans in our community.
On today's episode, we follow up on a recent webinar I co-hosted with VCP Co-Founder & Chief Project Officer Brandonn Mixon and Keen Wealth Senior Financial Planner Jeb Flynn and discuss giving strategies that can help folks do the most good for the causes that matter most.
Giving Without Itemizing
When the Tax Cuts and Jobs Act of 2017 significantly increased the standard deduction, it simplified filing taxes for the majority of Americans. Over 90% of taxpayers now take the standard deduction rather than gathering up receipts every year and itemizing.
But taking the standard deduction also means that most folks don't get the same tax benefits for charitable giving they once did. Take the standard deduction and write a big check to your favorite charity and the only benefit to you is the good you're doing.
If that sounds like the wrong way to think about giving, from a financial planning perspective, it's not. Even without itemizing deductions, there are other parts of our tax laws that incentivize giving. Building a comprehensive strategy around these rules can help you give more and even create a sustainable philanthropic mission.
Strategy 1: Qualified Charitable Distributions (QCDs)
Seniors age 70½ and older can make qualified charitable distributions (QCDs) from a traditional IRA directly to a qualified charity. Because the money never hits your bank account, the IRS doesn't consider these withdrawals taxable income.
However, once you turn 73 (or 75 if you were born in 1960 or later) QCDs do count towards your annual required minimum distributions (RMDs). So, if you do have to take money out of your IRA, but you don't really need it and you don't want to pay taxes on it, you can make a tax-free donation instead.
Strategy 2: Donor-Advised Funds (DAFs)
A donor-advised fund (DAF) is a charitable account that you control. The money you put into a DAF can be saved or invested in the account until you're ready to make a donation. But once you've put money (or other assets, see below) in the DAF, it cannot be taken out except for giving to a qualified charity.
DAFs have grown in popularity as folks look for tax-smart ways to maximize their charitable giving. If you have long-term giving goals, you might consider "bunching" several years of planned giving into a DAF, potentially allowing you to receive a larger charitable deduction in the year you make the contribution.
And you don't have to fund a DAF with cash. Donating highly appreciated securities can be particularly powerful. Rather than selling the securities, paying capital gains taxes, and then donating the cash, you can contribute the securities directly to a DAF. If the requirements are met, you can generally avoid capital gains tax on the appreciation while potentially receiving a charitable deduction based on the fair market value of the securities. That can leave more money available for the charities you want to support.
For example, let's say you plan to give $10,000 to a charity annually for the next five years. If you deposit $50,000 into your DAF, that could push you above the standard deduction threshold for that year. So, in year one, you could itemize and potentially receive a deduction for the $50,000 contribution, recommend a $10,000 grant to the charity, and then recommend $10,000 per year for the next four years while taking the standard deduction in those years.
If your giving goals are more modest than that, opening a DAF still could help you optimize your resources. The minimums to open a DAF are low at many financial institutions. And your DAF could also be a way to rally your family around a shared charitable mission.
Strategy 3: Donating Non-Cash Assets
If you're charitably inclined and you have assets like real estate or securities that have appreciated significantly, donating those assets rather than selling them first could help you avoid significant capital gains taxes.
As we discussed with donor-advised funds, highly appreciated securities can be especially attractive assets to give. Instead of selling the security, recognizing the gain, and donating the after-tax proceeds, you may be able to donate the security directly, avoid recognizing the capital gain, and potentially receive a charitable deduction for its fair market value.
There's another potential planning benefit as well. If you were going to make a charitable gift with cash anyway, you could instead donate appreciated securities and use that cash to purchase the same or similar investments. That allows you to maintain your desired investment exposure while resetting your cost basis higher for a potential future sale.
Plan Your Mission
I’ve seen firsthand how incorporating charitable goals into a comprehensive financial plan can give folks a renewed sense of purpose, especially in retirement.
As you’re considering one of these strategies, the team at Keen Wealth can help you decide on a giving strategy that makes philanthropy a fulfilling part of your life and an enduring part of your legacy.

About Bill
Bill Keen is a financial advisor with over 30 years of industry experience. As the founder and CEO of Keen Wealth Advisors, a registered investment advisory firm, he focuses on providing personalized retirement planning designed to help people thrive before and during their retirement years. With a passion for educating others, Bill regularly blogs about retirement planning, hosts the podcast Keen on Retirement, and has contributed to Forbes, U.S. News and World Report, Reuters, Wall Street Journal’s Market Watch, Yahoo Finance, and other publications. Based in Overland Park, Kansas, Bill and his team work with clients throughout the greater Kansas City area and across the nation. To learn more, connect with him on LinkedIn or visit www.keenwealthadvisors.com.
KWMG, LLC’s dba Keen Wealth Advisors (“company”) is an SEC Registered Investment Advisor located in Overland Park, KS. The company and its representatives may only conduct business in those states where registered or where excluded/exempt or from licensure. For registration information, please contact the SEC or the state securities regulators for the states where the company is notice filed. A copy of the company ADV is available upon request. Advisory services are only offered to clients or prospective clients where the company and its representatives are properly licensed or exempt from licensure. No advice may be rendered by the company unless a client service agreement is in place. This information is not intended to be investment advice or construed as a recommendation or endorsement of any particular investment or investment strategy and is for illustrative purposes only. Clients and prospective clients must consider all relevant risk factors involved with each strategy, including costs or fees, and their own personal financial situations before trading.
The views outlined in the book, Keen on Retirement Engineering the Second Half of Your Life, are those of the author and should not be construed as individualized or personalized investment advice. Any economic and/or performance information cited is historical and not indicative of future results. Economic forecasts set forth may not develop as predicted.
The Amazon Best Seller ranking listed on marketing materials is specifically referring to Best Seller rankings for the Kindle Top 100 Paid Lists under the subcategories of: Budgeting and Financial Risk Management, based on data as of September 5, 2019 and the second edition under Financial Risk Management on October 26, 2022. Amazon rankings although relevant on how a product is selling overall doesn’t necessarily indicate how well an item is selling among other similar items or similar item categories. Amazon may choose the most popular categories or subcategories within which an item has a high ranking to determine its best seller rankings. These rankings are updated hourly and as a result, should be expected to fluctuate as such. Keen Wealth Advisors and Amazon are not affiliated entities.
The Steve Sanduski Advisor Network, Belay Advisor, LLC and other third-party contributors to our blogs and podcasts are not affiliated with Keen Wealth Advisors.
For additional details on Keen Wealth Advisors, please visit https://www.keenwealthadvisors.com/important-disclosures.
20260923-5950642-18969897